
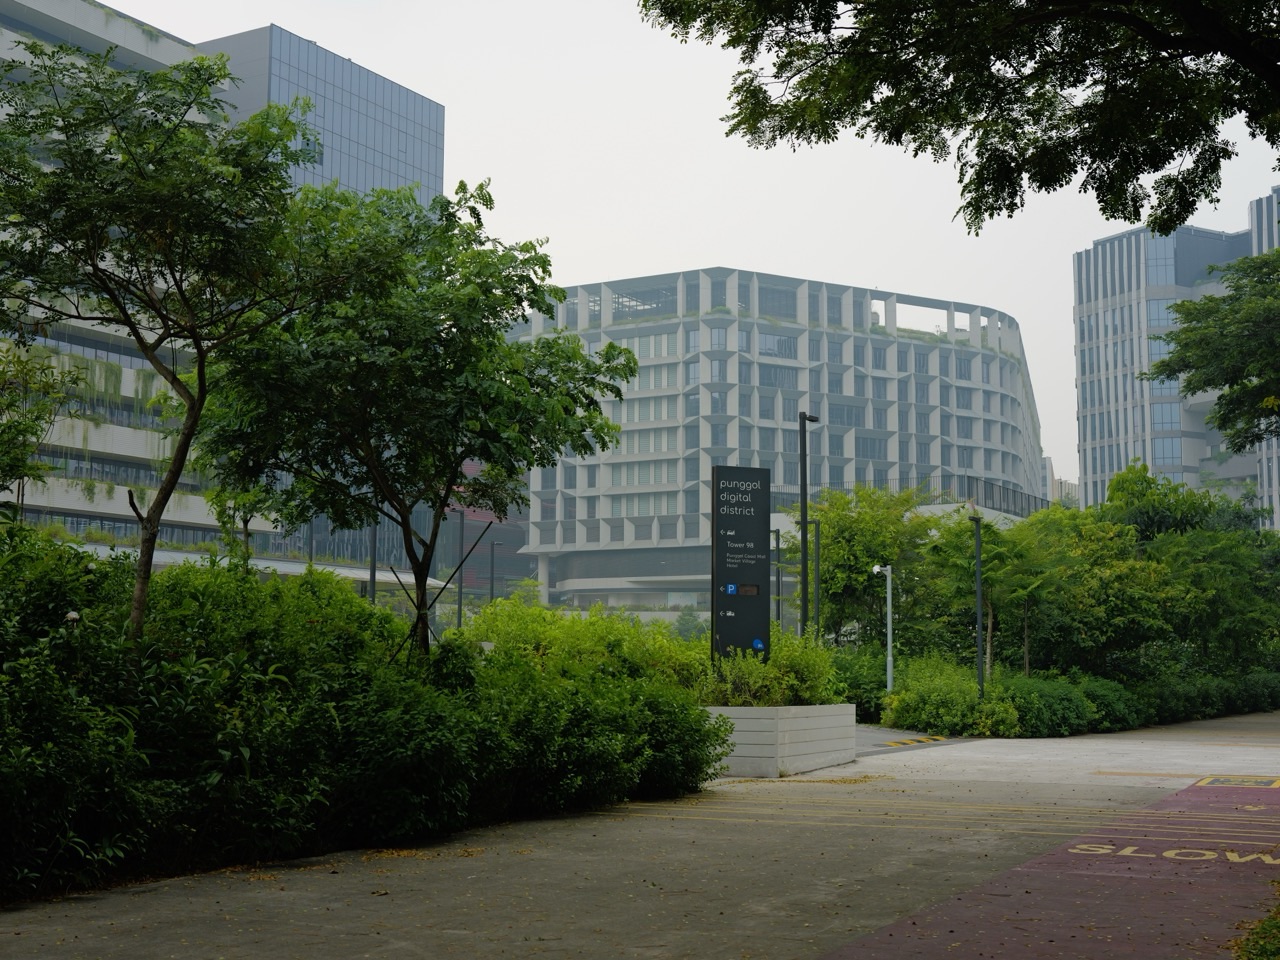
A business in Punggol Digital District may need software developers and engineers, but it also needs accurate accounts, payroll, tax records and company administration. This creates a practical professional-services market for firms based in Punggol, Sengkang, Pasir Ris and nearby Seletar from 2027 to 2037. The opportunity is not simply to advertise “we do everything for SMEs.” Ordinary bookkeeping, statutory audit, corporate filing as a service and payroll processing have different responsibilities. A supplier needs to identify its lawful scope, protect confidential information, price actual work and show that its clients can meet real deadlines without confusing a bookkeeping subscription with public accountancy or licensed corporate services.
As at 2 November 2026, ACRA states that the Corporate Service Providers Act took effect on 9 June 2025, requiring businesses providing defined corporate services in or from Singapore to register as CSPs and meet anti-money-laundering and related obligations. ACRA separately explains that auditing and reporting on financial statements requires registration as a public accountant, whereas ordinary bookkeeping and general accounting do not by themselves require that designation. IRAS’s current GST rules generally require registration when taxable turnover exceeds S$1 million under the applicable retrospective or prospective test. MOM also requires itemised payslips for Employment Act-covered employees and timely CPF contributions. A Punggol professional-services company must understand these separate obligations before promising compliance.
- Industry: Bookkeeping, management reporting, payroll administration, tax preparation, company secretarial and appropriately authorised corporate services.
- Local buyers: Punggol Digital District SMEs, retailers, landlords, engineering subcontractors, employers and other companies across north-eastern Singapore.
- Regulatory distinction: CSP registration for defined corporate services; ACRA public accountant registration for statutory public accountancy work; ordinary bookkeeping is not the same regulated activity.
- Employer obligations: Accurate pay records, itemised payslips, relevant CPF contributions and appropriate employee data handling.
- Tax: IRAS GST compulsory-registration tests, corporate tax recordkeeping and correct invoice reporting where applicable.
- Business model: Defined monthly retainers, properly scoped projects, compliant filing services and authorised technology implementation.
- Main risks: Missed deadlines, inaccurate records, customer data exposure, underpriced work, unqualified audit claims and dependence on a few clients.
- 2027–2037: A planning horizon for recurring professional service—not an official projection of Punggol business registrations or profit.

Why professional administration is an industry, not office paperwork
Small businesses often concentrate on selling their products. Yet those sales create invoices, payments, supplier bills, employment records and statutory obligations. A shop owner can run a profitable-looking operation and still struggle if cash flow is poorly tracked or obligations are missed. Professional service providers help convert everyday transactions into reliable information.
Different customers need different levels of support. A new freelance consultancy may need a simple accounting process. A manufacturer employing many workers may need payroll controls, inventory costing and management reporting. A company filing changes to its corporate register may need a registered CSP. A statutory audit belongs with a duly registered public accountant and accounting entity. These roles should not be bundled casually under one vague promise.
Punggol creates a local client base without guaranteed contracts
Punggol Digital District brings technology companies, financial institutions and SIT into a growing commercial setting. Neighbourhood retail and service businesses are also active around the estate. Some will buy accounting support locally because meetings and rapid communication are convenient. Others may use centralised national firms or cloud services. A startup should not assume that proximity to a commercial tower creates automatic access to its tenants.
A useful first market might be five or ten smaller organisations with recurring recordkeeping problems. The founder can interview genuine prospects about what they do internally and what they outsource. A service wins when it helps a buyer meet obligations, understand cash and reduce avoidable mistakes. It does not win simply because its office is located inside the same planning area.
What the CSP Act changed in June 2025
ACRA’s Corporate Service Providers Act 2024 took effect on 9 June 2025. It requires entities carrying on defined corporate services in and from Singapore to be registered with ACRA. The scope includes business formation for others, provision of registered addresses in applicable circumstances, nominee arrangements, designated accounting-related activities and specified ACRA filing services. Registered CSPs must meet associated legal obligations, including AML, counter-terrorism financing and proliferation financing controls.
A founder should read ACRA’s “Checking if you must register” guidance before offering paid corporate filing or company secretarial services. An accountant who also files company returns for customers may fall within CSP obligations even where ordinary bookkeeping alone would not. Some specific persons or arrangements have stated exemptions or treatment. The service performed—not the firm’s marketing title—determines what to evaluate.
General bookkeeping is different from public accountancy
ACRA explicitly explains that ordinary bookkeeping, general accounting, tax preparation and business advisory services do not by themselves require registration as a public accountant. Statutory auditing and reporting on financial statements, however, are public accountancy services that require the proper registration. A small business should never tell customers that its bookkeeping clerk is a licensed auditor merely because that employee prepares a trial balance.
This distinction creates legitimate niches. A skilled bookkeeper can help reconcile records and organise management information. An authorised CSP can handle specified corporate transactions under applicable rules. A public accountant and registered accounting entity can perform appropriate audit work. Where clients need several services, the provider should use clearly authorised professionals and explain who is accountable for each deliverable.
A company secretary is a real legal role
ACRA’s guide for local companies states that a company secretary must be appointed within six months of incorporation. The secretary helps with appropriate corporate governance and records, but that does not remove directors’ statutory duties. A firm selling company-secretarial services needs to understand who may perform the function and whether CSP registration applies to the business activities it carries out.
A provider should not market incorporation as the entire lifecycle of a company. Annual returns, changes to officers, maintained registers and other obligations can continue for years. The customer needs clear guidance about what is included, who signs required statements and what deadlines apply. Good corporate administration creates reliable records rather than merely uploading forms.
Company registration and corporate filing are not interchangeable
Registering a new business is one event. Filing annual returns, changes to company particulars and maintaining statutory registers are separate ongoing activities. A supplier should provide accurate descriptions of each service and who is legally authorised to transact. ACRA has specific provisions for filing on behalf of others and for company secretaries acting by way of business.
An entrepreneur should avoid accepting a client’s portal credentials and filing casually without the proper arrangement. Authorised access, client identity verification and record retention matter. A professional filing service can prevent avoidable mistakes, but its value comes from genuine compliance and documented responsibility.
AML and beneficial-owner checks add real operating cost
CSP businesses must comply with applicable anti-money-laundering and related obligations. These may require customer due diligence, identification of ownership structures, risk assessment, monitoring and appropriate records. A small provider should not treat these controls as decorative forms copied into a folder once at incorporation.
Staff must understand what suspicious circumstances require escalation and what information may be used. An automated identity check is only one component of a compliance process. A service that underprices filing work while ignoring these obligations can be financially and legally fragile. Buyers should know that a reputable CSP may ask questions before accepting an engagement.
Payroll administration begins with accurate employment data
Payroll is not merely typing a monthly salary into a spreadsheet. The employer may need to account for employment terms, basic wages, allowances, deductions, overtime, leave, public holidays, CPF and other obligations depending on the employee. A provider can process information, but it needs correct authorised inputs and a clear approval process before payment.
A payroll service should define whether it only calculates amounts or also prepares bank-payment files and statutory submissions. The employer must understand which obligations remain with it. The supplier should not silently change bank details or authorise transfers outside its agreed remit. Clear segregation of duties reduces both honest errors and fraud risk.
MOM itemised payslip rules are concrete
MOM requires employers to issue itemised payslips to employees covered by the Employment Act. Payslips generally accompany salary payment or must be provided within three working days if not possible at the same time, with different timing on employment termination. MOM lists the information employers must include, such as basic salary, salary period, allowances, deductions, overtime where applicable and net pay.
A payroll software supplier should test its output against the relevant requirements rather than claim every downloaded template is compliant. Rules can differ by employee category and circumstances. Accurate payslips help workers understand earnings and can prevent disputes. The business value lies in correctly completed records that employers and employees can verify.
CPF deadlines are not a software feature
MOM and the CPF Board explain employer contribution obligations. Contributions are due at the end of the month, with penalties possible if payment is not made by the 14th of the following month. The correct contribution depends on employee status, age and other applicable rules. A provider processing payroll needs a method for identifying changes and obtaining confirmation.
A software company should not promise that activating automatic calculation eliminates the employer’s duty to review and pay. If bank details or employee status are wrong, the outcome may still be wrong. A responsible service uses reconciliation and clear approvals, and notifies the customer promptly about missing inputs. It should never conceal a failed statutory submission behind a green dashboard icon.
GST registration is not based on business age
IRAS describes compulsory GST registration under the retrospective and prospective taxable-turnover tests. The general threshold is more than S$1 million of taxable turnover, but the timing, exempt supplies and special registration rules matter. A new company may have to register if it reasonably expects to cross the threshold within the next twelve months, even without a long trading history.
A bookkeeping or tax support provider should understand the criteria and refer complex cases to a competent adviser. It must avoid telling every small business that GST registration is optional regardless of revenue. At the same time, not every company making S$1 million in total receipts necessarily has an identical taxable turnover computation. Accuracy requires checking the relevant definitions.
InvoiceNow adds a technology integration market
ACRA’s local-company guidance highlights IRAS’s GST InvoiceNow Requirement, which phases in transmission of invoice data through the InvoiceNow network for specified GST-registered businesses. The relevant implementation dates depend on the business category and when it registers. A software integrator may help companies prepare compliant electronic invoicing workflows, but should verify the actual current IRAS timetable.
A founder should not market an ordinary emailed PDF as automatically satisfying every InvoiceNow requirement. Enterprise integration may involve accounting software, access permissions and accurate invoice data. A narrow and verified implementation service can be valuable. Its financial model must include testing, customer training and support after the initial setup.
Management accounts are for decisions, not just filing
A small business may need profit-and-loss statements, cash-flow information and a clear list of unpaid invoices. These records help its owner decide whether to hire, raise prices or reduce a costly service. A bookkeeping provider can contribute more than compliance by delivering understandable, accurate management reports.
The key is to distinguish recorded facts from forecasts. A report showing actual expenses is not the same as a projection of next year’s revenue. A service provider should explain assumptions and uncertainties. Some customers prefer a brief monthly discussion of three critical figures over a large dashboard nobody reads. Useful reporting supports decisions rather than simply producing documents.
Bank reconciliation is a valuable recurring task
Many errors emerge when recorded sales or bills do not match bank transactions. A reconciler can help identify duplicates, timing differences and missing documents. The process should preserve original records and ensure that unexplained amounts are not simply labelled as miscellaneous expense. A bookkeeping company should define the evidence needed from the customer before closing each period.
A careful review can uncover late invoices and cash-flow risks. It can also reduce time spent preparing financial statements or tax information. The commercial value is accuracy and clarity, not just speed. A provider that posts convenient guesses to make the balance appear correct can create larger problems for the client.
An accounting application needs a human review process
Cloud accounting software may automate data imports and categorisation, but rules and machine learning can misclassify transactions. The customer may still need to determine whether a payment is capital expenditure, a deductible expense or another category under applicable rules. A professional services firm should not promise that AI eliminates the need for competent accounting judgment.
A reliable workflow allows staff to examine exceptions and correct errors with an audit trail. The provider should maintain change logs and explain which reports have been reviewed. An automated draft can be a productivity tool without becoming an authoritative tax opinion. Human accountability is a major part of the service.
Confidentiality is central to a payroll or accounting firm
Providers may see client bank statements, employee salary records, customer information and confidential plans. Data should be accessed only for defined purposes and protected under applicable law and contracts. A payroll firm must not use employees’ salary details for unrelated marketing or share one customer’s records with another.
A new company should establish suitable access control, encryption or other safeguards, secure document handling and prompt revocation when staff leave. Use fictional records for demonstrations. The trust involved in handling client finances is often more important than proximity to the customer’s office. A single careless disclosure can damage years of reputation.
Staff competence and supervision cannot be replaced by templates
A small firm may hire junior staff to prepare records and have an experienced person review complex matters. This can be efficient when responsibilities are clear. It becomes dangerous when every unfamiliar transaction is automatically categorised without review. Training and escalation procedures are essential.
A professional service should define which work junior staff may perform and what requires a senior, registered CSP or public accountant. Clients should know who handles their engagement. The founder needs enough time for quality checks, not just sales and invoicing. A sustainable business invests in competent people and a culture where errors can be reported and corrected.
Pricing one-off and recurring services differently
An incorporation engagement may involve a defined package, while monthly bookkeeping creates recurring work. Payroll cost can vary with employee count and complexity. Company secretarial services may include periodic filings, but unusual changes can require extra effort. A professional provider should set clear scopes rather than offer unlimited compliance services for an unrealistically low flat fee.
A useful quotation specifies which entities, transactions or employees are included, what documents the customer must provide and how extra work is priced. The firm should explain whether tax filing, statutory audit or CSP activities are separate. Customers can then compare offers fairly and avoid surprise charges. The provider protects its own margins by refusing undefined obligations.
A hypothetical monthly bookkeeping model
Imagine a small professional-services company managing twenty clients at an average monthly fee of S$800. Gross revenue is S$16,000. Staff and review time costs S$8,500, software and secure storage S$1,400, and client service, insurance and compliance allocation S$2,000. The illustrative contribution is S$4,100 before other overhead and tax.
These are teaching figures, not Punggol market quotations. If five customers unexpectedly need extensive cleanup or complex regulatory advice, the allocated staff cost may rise sharply. A business should measure actual hours and scope changes, not assume every monthly retainer has the same cost. Clear client records and good onboarding can improve repeatability.
Payroll clients can be expensive when records are incomplete
A payroll package may be priced per employee, but a company with complex shifts, allowances and late changes may need far more work than a simple salaried workforce. A provider should obtain a realistic picture of the client’s payroll arrangements before quoting. It should also identify who validates overtime and approves last-minute adjustments.
If information arrives only on payday, the service may be forced into rushed work and higher error risk. A contract should set cut-off dates and exception procedures. A client that consistently submits records late may need a different pricing or process arrangement. The goal is accurate payment to employees, not simply closing a monthly ticket.
Client onboarding is a financial-control project
Switching accounting providers requires more than exchanging passwords. The new firm needs opening balances, transaction history, current filing status, employee and supplier information where relevant, and an agreed date for responsibility transfer. Poor handover can create duplicate entries or missing obligations.
A good provider uses a checklist and documents unresolved items. It should not pretend to have verified accounts it has not reviewed. A client may need additional cleanup work before normal monthly service begins. Quoting and billing that project separately can prevent ongoing disputes and protect the quality of future reports.
Professional independence matters in audit work
Statutory audit is not a decorative annual signature. A registered public accountant must follow applicable professional and independence requirements. A company providing bookkeeping and audit services should understand whether conflicts or ethical restrictions arise. A founder should never suggest that the person who prepared records can automatically sign an independent audit without considering those obligations.
A small firm that does not perform public accountancy can still serve customers through bookkeeping and management support, while referring appropriate audit work to duly registered providers. An honest division protects the customer and the credibility of the profession. Trying to offer every service under one name without the required authority creates risk.
Tax preparation needs accurate client facts
A service provider may prepare information for corporate income tax, GST or other filings, but its work depends on valid records and actual circumstances. A company should not use the same generic tax deduction assumptions for every client. Some industries have specialised rules, and changes in legislation can affect the result.
A responsible provider tracks source documents, assumptions and review decisions. If a client asks to omit a sale or invent an expense, the firm should not comply. A short-term fee earned through incorrect filings can create substantial long-term problems. Professional credibility includes telling a customer when a proposed treatment needs further advice.
The financial year and filing calendar must be managed
Companies may have different financial year ends, annual return schedules and filing obligations. A provider needs a calendar specific to each client rather than one generic date for everyone. ACRA and IRAS publish current rules; the firm should verify them instead of repeating outdated deadlines. A missed date may create penalties or additional work.
A useful software tool can send appropriate reminders, but the supplier must know which duties apply and who is responsible for acting. A reminder is not a completed filing. The service should confirm acceptance and retain the relevant record. This is a practical way technology can help professional administration without replacing the underlying responsibility.
Invoice automation can reduce errors but increase integration risk
When a company uses accounting software, a bank feed and an invoicing platform together, inconsistent data can create duplicate or missing entries. An integrator can help design a controlled workflow. But it should not assume that every business uses compatible systems or that direct bank access is permitted.
A prototype can use sample invoices and payments to show how reconciliation works. Live integration requires customer authorisation, security review and testing. A useful system preserves source records and highlights uncertainty instead of silently altering figures. The customer should be able to export data when the service ends. Reliability and portability are important selling points.
Advisory work has different commercial consequences
A founder may ask a professional services firm to help forecast cash or compare expansion options. This is more than recording transactions. It requires assumptions about future sales, staffing and costs. The provider should explain those assumptions and avoid implying that a forecast is guaranteed. Advice also needs to stay within the professional’s actual competence.
A credible advisory deliverable might compare three scenarios and identify cash runway under each. The business owner retains responsibility for commercial decisions. A provider adds value by making uncertainty visible rather than promising that a particular investment will succeed. Good advice can prevent costly overexpansion.
A fictional Punggol digital-services customer
Imagine a small software company near Punggol Digital District employing six people and billing several business clients. It needs accurate monthly accounts, payroll and a clear picture of unpaid invoices. A bookkeeping firm defines an appropriate service scope, collects records securely and prepares reconciled management reports.
If the client later needs corporate filing, the provider ensures that the service is carried out under the correct CSP arrangement. If statutory audit is needed, a duly registered public accountant is involved. The client receives clear responsibility boundaries rather than one vague package. This is a realistic professional-services relationship.
A fictional payroll specialist
A startup specialises in payroll administration for small service employers. It builds procedures for input checks, payslips, CPF review and management approval. The service does not automatically make employment-law decisions for clients and does not claim to be a registered CSP unless its activities require and satisfy registration.
The company prices monthly work according to complexity, not just headcount. It offers clear cut-off times and support for corrections. When an unusual issue arises, it identifies the appropriate professional advice rather than guess. A narrow, dependable service can create recurring revenue without expanding into unauthorised activities.
A fictional corporate filing business
A founder plans to assist companies with incorporation and annual returns. Before advertising, the business assesses whether CSP registration is required and completes the applicable requirements. It establishes customer identity, due diligence, records and filing controls. It does not simply use a customer’s personal login to bypass the formal process.
The firm can then quote its legitimate services, including ongoing obligations and exclusions. Customers know who is filing and what documents must be provided. This model requires more compliance work than a casual filing service, but accuracy and accountability are part of what clients pay for.
A fictional accounting software integrator
An IT company wants to help retailers connect invoices, payment records and approved accounting tools. It works with genuine customer permission, uses synthetic data for initial testing and documents integration limitations. It does not claim to provide statutory audit or tax advice merely because its software calculates a number.
Its customers may pay for setup and training, with separate maintenance arrangements. The company measures whether bookkeeping errors and administrative time fall. If the workflow creates more mismatches than it solves, the vendor revises it. This is a technology supplier role within the professional-services value chain.
2027–2029: grow around real compliance and reporting needs
The early period follows implementation of the CSP Act and phased invoicing changes. A new service firm should verify current requirements, select a precise niche and build reliable internal controls. An accounting firm may find customers among technology startups, retailers and industrial SMEs, but each must be won through genuine value.
The founder should focus on accurate work, timely communication and sustainable pricing. A few well-served clients can create a stronger reputation than dozens of underpriced subscriptions. If the firm lacks authorisation for a particular activity, it should not accept it and hope to obtain credentials later. The goal is a repeatable service that stays within the law.
2030–2033: standardise the process without erasing judgment
A growing firm may introduce automation and employ additional staff. It needs common procedures, quality review and a way to handle exceptional cases. Some clients will have more complex entities or payroll arrangements, requiring specialised oversight. A standard subscription should not conceal material differences in scope.
The business can measure turnaround, reconciliation quality and customer retention. Technology may reduce data entry while increasing the importance of data protection and audit trails. A company should resist promising that AI will eliminate all professional responsibility. These dates are planning checkpoints, not an official forecast of the number of businesses in Punggol.
2034–2037: preserve trust when technology and rules change
Accounting software and corporate reporting rules may evolve during a decade. A provider should be able to update methods, train employees and migrate client records safely. A firm dependent on one proprietary platform may need a continuity plan if that provider changes pricing or support. Customer relationships should not depend on obscuring data or making exit difficult.
The long-term advantage is dependable records, timely service and sound professional boundaries. No one can guarantee a fixed retainer margin through 2037. A resilient company understands its real work, charges fairly and protects client information throughout the relationship.
Checklist before offering accounting or corporate services
- Which services are bookkeeping, payroll, corporate filing, taxation, advisory or statutory audit?
- Does the business need ACRA CSP registration for its actual activities?
- Are public accountant or other professional authorisations required for any promised work?
- Who approves filings, payroll payments and bank instructions?
- Have client identification and applicable compliance checks been completed?
- Are GST thresholds, deadlines and employment obligations correctly assessed?
- Which sensitive financial and employee records may staff access?
- Can the customer verify each filing or submission was accepted?
- Does the monthly fee cover the true level of work and review?
- How are unusual transactions, errors and missing documents handled?
- Can the firm provide suitable staff cover during leave or illness?
- Does the software keep records traceable and permit secure export?
- Are marketing claims about licences and qualifications accurate?
- What happens when the client changes service provider?
A professional-services firm that can answer these questions offers more than administrative convenience. It supports the reliable operation of its customers’ businesses. The industry rewards accuracy, confidentiality and clear accountability rather than broad promises of effortless compliance.
Frequently Asked Questions
Must every bookkeeper register as a corporate service provider?
Not merely because they provide ordinary bookkeeping. ACRA’s CSP registration rules apply to defined corporate services and designated activities. A firm that also conducts corporate filing or other covered work should check the precise requirements.
Is general accounting the same as statutory auditing?
No. ACRA states that auditing and reporting on financial statements require the proper public accountant registration. Ordinary bookkeeping and general accounting do not by themselves confer that authority.
When must a Singapore company appoint a secretary?
ACRA states that a company secretary must be appointed within six months of registration. Other company obligations and the requirements applying to CSP service providers should be reviewed separately.
Is GST registration automatically optional for every small company?
No. IRAS uses compulsory registration tests based generally on taxable turnover above S$1 million, with relevant timing and special rules. A company should assess its actual circumstances.
Can payroll software guarantee complete employment-law compliance?
No. Payroll depends on accurate employment data, correct rules, approval and timely submissions. Employers retain applicable obligations and may need professional advice for complex cases.
Will professional administration businesses be profitable through 2037?
No. Customer acquisition, compliance cost, labour, software, competition and service quality determine results. A ten-year plan helps manage change but cannot guarantee income.
Your Next Step: define the lawful service and measure its real cost
Begin with one customer problem—such as inaccurate monthly bookkeeping or difficult payroll reconciliation. Identify what the client will actually buy and which professional or CSP registration rules apply. Build secure procedures and a clear scope before quoting. Test full costs, including review, confidentiality and client support. A Punggol professional-services business becomes valuable when its customers can trust the records and deadlines, not merely because a software system displays a green compliance status.
Official sources: ACRA Corporate Service Providers Act, ACRA CSP registration assessment, ACRA public accountant requirements, ACRA local company post-registration guide, IRAS GST compulsory-registration tests, MOM itemised payslip rules, and MOM employer CPF contribution guidance. Rules and client-specific obligations should be checked when services are actually provided.


